
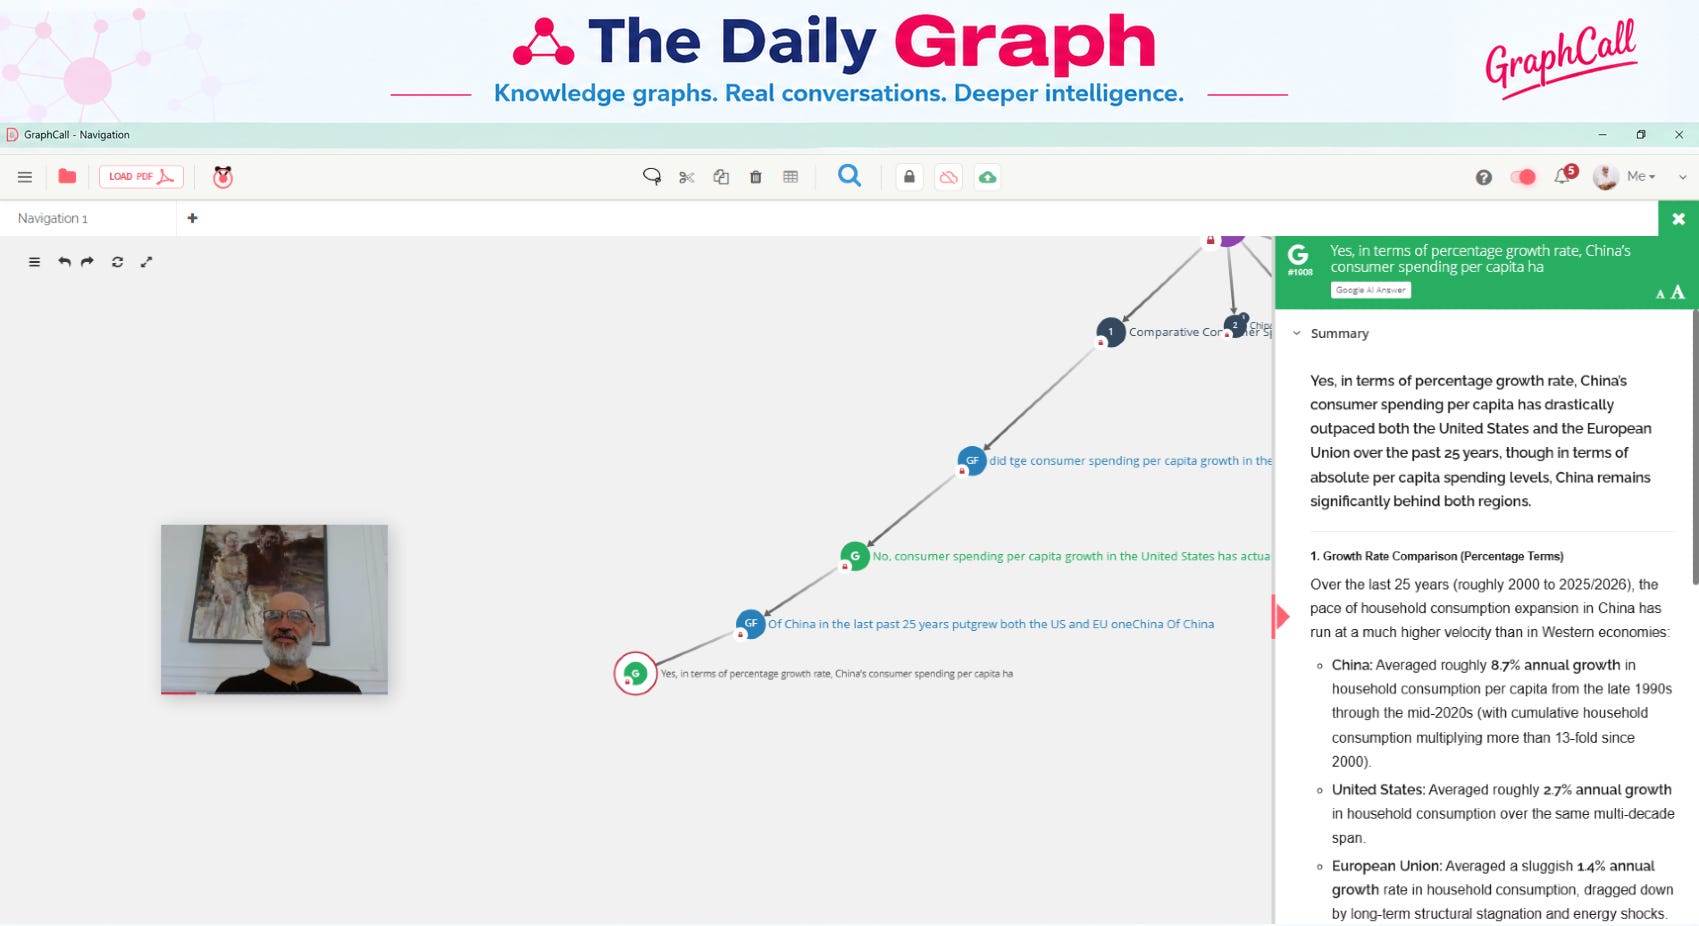
China is not Japan. Real estate, micro-credit and COVID scars are masking structural strengths. Unlike Japan, China is not recycling its trade surplus into foreign assets, while EV adoption reduces the income exported to pay for oil. Savings build productive capital, ultimately driving productivity, lower prices and rising real purchasing power. Meanwhile, China is emerging from a credit bust, while the US increasingly displays late-cycle excesses. The investment opportunity lies in recognising
Today's AI capex excess and Bitcoin's 'fixed money' delusion echo the 1847 financial crisis. Excessive capital spending crowds out other investments, straining consumers. Just as historical fixed-money policies caused havoc, today’s trade imbalances disrupt traditional interest rate mechanics. When trading partners refuse to recycle surpluses into US debt, they buy gold instead. High rates only work by lowering domestic prices to settle trade, explaining modern tariff pushes.
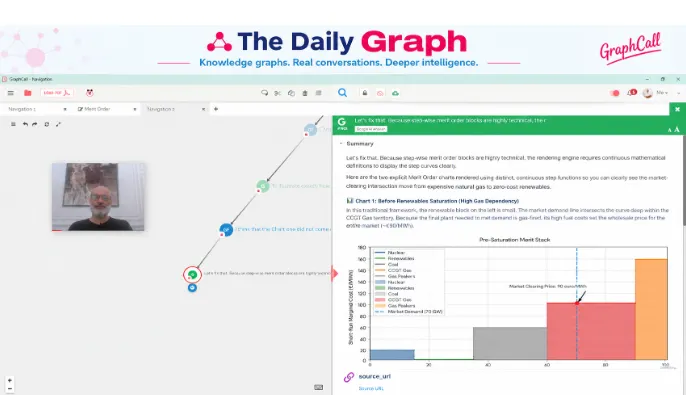
Merit Order power pricing, bi-directional power charging and discharging.
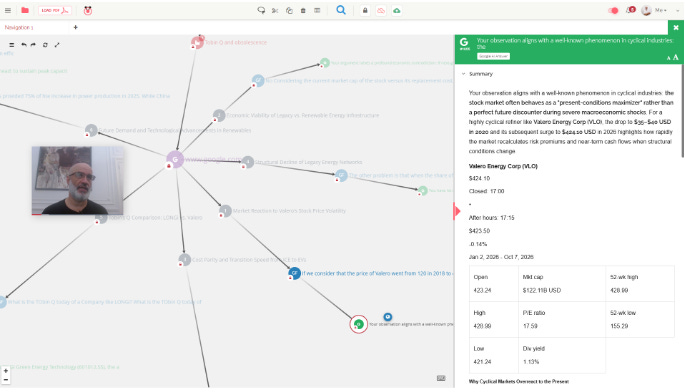
Valero and LONGi are not only at the opposite spectrum of who is going to be powering transportation in the future but ALSO have an opposite set of circumstantial elements (the present) versus structural elements (the likely path in the future given the evolution of costs)
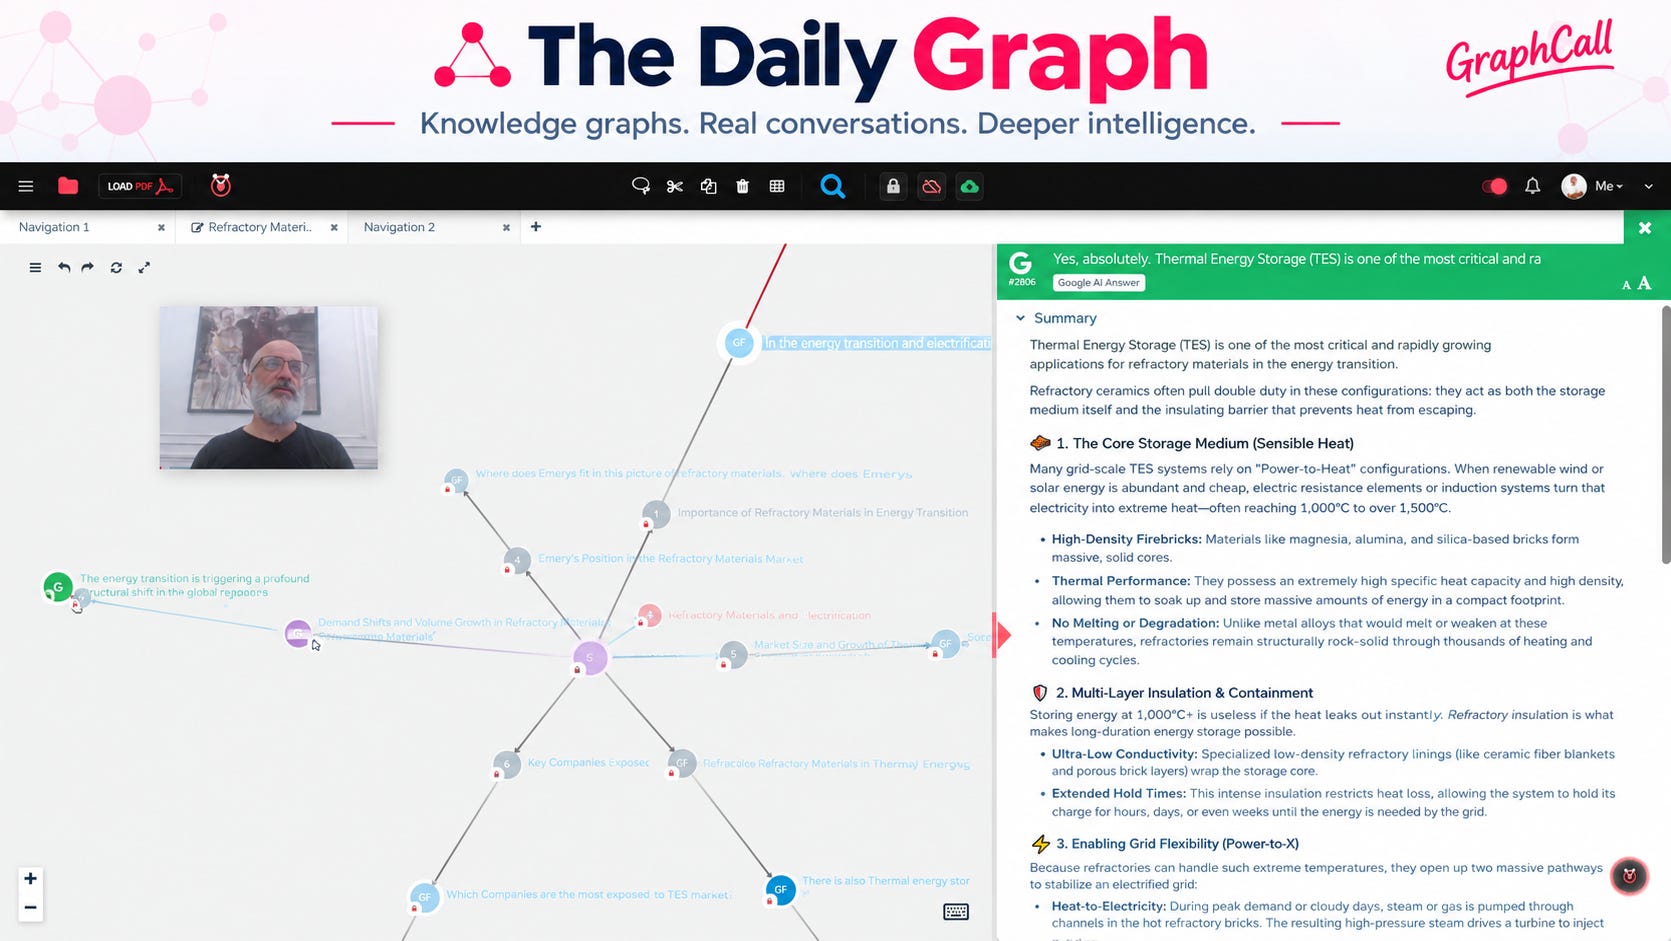
About electrification and Refractory Materials


How to stimulate EV substitution in EUrope by bombing Russian diesel Refineries.

The discussion examines whether interest rate hikes can still tame inflation when the U.S. runs a persistent 2.6% primary deficit. Higher rates suppress demand but also increase government interest payments, creating a liquidity injection to bondholders. The analysis compares today's globally held debt market with the post-WWII era, explores how Treasury issuance shifts toward T-Bills amplify liquidity, and argues that Japan's Treasury sales and Fed backstops may further dilute monetary tighteni